
Crypto Taxes Made Easy
Taxes on crypto can be a bit confusing. Don’t worry, though! This guide will break it all down for you in easy steps. We’ll make it simple, and even a little fun!
Imagine buying a toy with your favorite game coins. It seems easy, right? Well, crypto is a bit like that, but when you trade, buy, or sell, there are rules. The IRS (the people who take care of taxes) wants to know when you make money from crypto. Sounds tricky, but we can handle it together!
We’ll guide you through everything you need to know. From when you have to pay taxes to how to keep track of your trades. It’s like a treasure map, and at the end, you’ll know exactly what to do with your crypto taxes. Let’s make this as easy as counting to ten!
Whether you’re selling Bitcoin, buying things with crypto, or mining coins, we’ve got all the steps to help you stay on top of your taxes.
What is Cryptocurrency Taxation?
Cryptocurrency is taxed like property. This started in 2014. The IRS decided that year. It means crypto is like owning stock. So, you report gains or losses. For example, if you sell Bitcoin, you might owe taxes. It’s like selling part of your house.
Now, crypto taxes are stricter. In 2023, new rules came. If your crypto deal is over $10,000, you must report it. The IRS is watching more closely. Even moving crypto between wallets needs records. Let’s say you move $20,000 of Bitcoin. Keep notes! The IRS can ask later.
In 2024, crypto use is growing fast. More than 25% of high-income people own crypto. Moving and trading crypto is common. The IRS wants to know every detail. By September 2024, the rules are even tighter. Imagine sending $15,000 in Bitcoin to a friend. You must tell the IRS.
Why Cryptocurrency is Taxed Differently
Crypto is very different from normal things. It isn’t taxed like regular money. Here’s a quick comparison:
| Crypto Assets | Traditional Assets |
| Taxed when traded or sold | Taxed when sold |
| Tracked by value changes | Often taxed on profits |
| Use can trigger capital gains | Only sales trigger taxes |
Crypto is special because its value changes fast. One day Bitcoin is worth $30,000, the next $28,000. This makes taxes a bit tricky. Imagine buying coffee with Bitcoin. You might need to pay taxes on that coffee! Crazy, right? So, you must track every crypto move.
By September 2024, crypto’s fast-changing value is causing lots of tax questions. More than 60% of crypto owners use it for shopping. Each time, the IRS wants to know! So, keep track of all your crypto buys, sells, and trades—even if it’s just for coffee!
Crypto changes in value fast. This makes taxes tricky. Unlike regular stocks, buying coffee with crypto can trigger a taxable event. So keep track of every transaction.
Key Taxable Events in Cryptocurrency
There are specific moments when taxes apply:
- Trading crypto: Every trade is taxable. Even swapping Bitcoin for Ethereum triggers taxes. For example, if you traded 0.5 Bitcoin for 5 Ethereum in 2024, and Bitcoin's price was $30,000 at that time, the IRS would calculate your gain or loss based on Bitcoin’s value when you acquired it. Even a small trade can lead to a tax bill. If you made a profit of $1,500, that’s taxable.
- Using crypto: Buying goods with crypto is like selling it. Say you bought a coffee for 0.001 Bitcoin, when Bitcoin was worth $27,000. If you originally paid $20,000 for that Bitcoin, you’ve made a $7,000 profit on the total amount, even for a small purchase like coffee. Taxes are due on the portion of profit involved in the transaction.
- Mining and staking: Mining or staking earns you income, which is taxable. In 2024, the average miner made around $15,000 a year. The IRS treats this as business income. For instance, if your equipment cost you $3,000, you can deduct that from your taxable income, reducing it to $12,000. However, you’ll still owe taxes on that $12,000.
- Gifting crypto: Giving crypto as a gift can trigger gift taxes. If the value of the crypto gift exceeds $17,000 (the 2024 limit), taxes apply. For example, gifting 0.6 Bitcoin at $30,000 means the value is $18,000, so you may owe taxes on that gift. But donations to charity can be tax-deductible, and reporting the donation helps reduce your tax liability.
Trading Cryptocurrency
All crypto trades are taxable. For instance, if you bought
1 Bitcoin
for
$20,000
and traded it for
20 Ethereum
when Ethereum’s price was
$1,800
in
2024
, your total Ethereum value is
$36,000
. That means you have a
$16,000
profit, which is taxable. The IRS doesn’t care if you didn’t sell it for cash, the trade alone is taxable.
Selling Cryptocurrency for Fiat Currency
Selling your crypto for cash, like
USD
, triggers taxes. If you bought
1 Ethereum
for
$1,500
and sold it for
$2,000
, you owe taxes on that
$500
profit. In
2024
, the IRS required full reporting on all crypto sales, no matter the amount.
Using Cryptocurrency for Purchases
Buying products with crypto is also taxable. For example, buying a laptop for
0.05 Bitcoin
when Bitcoin is worth
$30,000
means you spent
$1,500
. If you originally bought that
0.05 Bitcoin
for
$1,000
, you have a
$500
profit, which is taxable, even though it was used for a purchase.
Earning Cryptocurrency as Income
If you earned
0.2 Bitcoin
from mining in
2024
, and Bitcoin’s value was
$25,000
, your total income from mining would be
$5,000
. The IRS requires you to report this as income, and self-employment taxes may apply. If you spent
$1,000
on electricity and equipment, you can deduct that, leaving you with
$4,000
in taxable income.
Gifting and Donating Cryptocurrency
When gifting crypto, if you give
0.7 Ethereum
worth
$2,000
to a friend in
2024
, no taxes are due if the gift is under
$17,000
. However, if you donate that
0.7 Ethereum
to charity, the donation might be tax-deductible. You can report the value as a deduction and lower your overall tax bill.
Types of Cryptocurrency Taxes
There are two main types of taxes for crypto:
- Capital Gains Tax: This is for when you sell or trade crypto. It depends on how long you held it. Short-term sales get taxed like regular income, while long-term sales usually have lower rates.
- Income Tax: This is for mining, staking, or earning crypto as payment. The IRS treats it like any paycheck. You report the value of the crypto when you receive it.
Both are important to understand, so you pay the right amount of tax!
Capital Gains Tax
This tax depends on how long you hold your crypto. Holding for more than a year means you pay less tax.
Here’s how it works:
- Short-term gains: If you sell within a year, you pay higher taxes. This is the same as your regular income tax rate.
- Long-term gains: If you hold for more than a year, you pay less tax. In 2024, most people pay around 15% on long-term gains. If your total income is under $44,626, you might not pay any tax on long-term gains!
For example, imagine you bought Bitcoin for
$10,000
in
January 2023
and sold it for
$15,000
in
February 2024
. Because you held it for more than a year, you pay long-term capital gains tax on the
$5,000
profit. This lower rate can save you a lot on taxes!
Income Tax
If you earn crypto, it’s treated like income. Whether you’re mining, staking, or getting paid in crypto, it counts as income. The IRS treats crypto just like a paycheck.
For example, if you earned
0.1 Bitcoin
for a job in
September 2024
, and Bitcoin’s price was
$27,000
that day, you report
$2,700
as income.
You need to report the value of the crypto on the exact day you received it. This applies to all forms of crypto income. Always check the price when you earn crypto, so you can report it correctly. Keep those records safe!
Self-Employment Tax for Crypto Miners
Mining crypto is like running a business. You owe self-employment tax on all earnings from mining. Just like owning a small business, you must report everything to the IRS.
For example, if you mined
$10,000
worth of Ethereum, that’s income. But if your mining equipment cost
$2,000
, you can subtract that from your earnings. This helps lower your taxable income.
In
2024
, many miners found that mining costs, like electricity, were high. You can also report these expenses to reduce your taxes. Keeping detailed records of these costs is key.
Miners should treat it like any business—track income and expenses carefully!
Calculating Your Cryptocurrency Taxes
Here’s a simple way to calculate your crypto taxes:
- Find the cost basis. This is what you originally paid for your crypto.
- Subtract the sale price. Take the sale price and subtract it from the cost basis.
- Report your gains or losses. You must tell the IRS about these.
For example, if you bought Ethereum for
$1,000
and sold it for
$1,500
, you made a
$500
profit. This
$500
is reported as a capital gain.
If you have many trades, it’s smart to use a crypto tax software like
CoinTracker
. In
2024
, over
50%
of crypto traders used tax software to stay organized and avoid mistakes. It makes calculating and reporting your taxes much easier.
Cryptocurrency Tax Reporting Requirements
You must report all crypto transactions to the IRS. Here’s a simple checklist to help:
- Report all trades. Even the tiny ones matter. Don’t leave any out.
- Include income from mining or staking. If you earn crypto this way, it counts as income.
- Keep records of everything. Even if a transaction isn’t taxable, you should still keep track of it.
In
2024
, about
60%
of crypto users had to report multiple trades. Staying organized is key to avoiding mistakes and penalties.
Cryptocurrency Tax Deductions and Exemptions
You can save on taxes if you had losses. Selling crypto at a loss helps lower your tax bill. You can deduct those losses from your total income.
For example, if you lost
$1,000
from selling Bitcoin, you can subtract that from your taxable income. This means you’ll pay less in taxes.
In
2023
, more than
35%
of crypto traders used losses to reduce their tax bills. It’s a smart way to pay less if you didn’t make profits.
You can also carry losses to future years. If your losses are bigger than your gains, you can use them later. This helps when crypto markets are tough.
Common Cryptocurrency Tax Mistakes
Be careful with these common mistakes:
- Not reporting all transactions. Every trade counts, even small ones. For example, selling 0.01 Bitcoin still needs reporting. Many forget these small trades, which leads to problems.
- Miscalculating cost basis. This means not knowing what you paid. For example, if you bought Ethereum for $1,500 and forget, you could report wrong numbers. It’s easy to make this mistake.
- Not keeping records. Always save your transaction details. If you sell Bitcoin after months, you need to prove what you originally paid. Without proof, taxes get tricky.
- Missing the IRS deadline. The deadline is strict and important. For example, filing after April 15th in 2024 means penalties. Always file on time to avoid fines.
In
2023
, nearly
25%
of crypto traders made these mistakes. Stay organized, track everything, and always file on time!
International Cryptocurrency Taxation
Countries have different ways of taxing crypto. In the
U.S.
, if you hold foreign accounts with more than
$10,000
in crypto, you must report it to the IRS. This rule is strict, and if you don’t report, there can be big penalties.
In
Australia
, crypto is treated like property. You pay taxes on your crypto gains, but if you hold it for more than a year, you get a discount. For example, long-term holders get up to a
50%
tax reduction in
2024
.
Japan
has some of the highest crypto taxes. In
2024
, profits can be taxed up to
55%
for top earners. This makes it tough for big traders, but it’s important to follow the rules to avoid fines.
In
Switzerland
, crypto is seen more like an asset. You only pay taxes if you earn income from it, like mining or staking. For many, this is a tax-friendly country for crypto investments.
How Different Countries Tax Cryptocurrency
Different countries have their own rules. Here's a simple comparison:
| Country | Tax Rate |
| U.S. | 10%–37% (income-based) |
| Germany | 0% for long-term holders |
| Canada | 50% on capital gains |
In the
U.S.
, taxes depend on your income. In
2024
, top earners may pay up to
37%
on crypto income. This means if you make a lot of money, your taxes are higher.
Germany
is more friendly to long-term holders. If you hold crypto for more than a year, you pay
0%
in taxes. That’s great for investors who don’t trade often.
In
Canada
, crypto gains are taxed differently.
50%
of your profits are taxed. So, if you earn
$1,000
, only
$500
gets taxed. It’s a fair system for many traders.
Each country treats crypto differently, so it’s smart to know the rules where you live!
Double Taxation Treaties
Some countries make special agreements to help you. These are called double taxation treaties. They stop you from paying taxes twice. Imagine earning money in one country and living in another. Without these treaties, you’d pay taxes in both places!
In
2024
, over
3,000 treaties
exist worldwide. They help millions of people who live or work across borders. For example, the
U.S.
has treaties with over
60 countries
. This helps Americans working abroad save money on taxes.
Countries like
Germany
and
France
have many of these deals too. They make sure you only pay taxes once on your income. This is super helpful if you’re traveling or working in different places.
It’s important to check if your country has a treaty with another. You can save lots of money and avoid paying twice!
Crypto Tax Tools and Resources
You can use many tools to help. They make taxes easier and less scary.
CoinTracker:
Tracks all your crypto trades. It’s super easy to use. Just connect your wallets. It shows your profits and losses. You won’t miss any details. Over
500,000 users
already trust CoinTracker.
TurboTax:
It helps you file your crypto taxes. You can add your trades, and it calculates everything. TurboTax makes sure you follow the law. In
2023
, over
70,000
crypto traders used TurboTax for their taxes. It helps with both small and big portfolios.
IRS Website:
This is the official place for tax info. They update their rules often. You can find guides about crypto taxes here. The IRS estimates that
10 million
Americans own crypto. They expect
5 million
more to file crypto taxes by
2025
.
These tools are here to help. Don’t stress over taxes! Use them, and you’ll be just fine.
Future of Cryptocurrency Taxation
The future of crypto taxes is changing fast.
By 2025, new rules will begin. Brokers will share more details. They will report everything to the IRS. This includes every crypto trade you make. Your transactions will be closely watched.
In
September 2024
, experts say that
over 50%
of crypto traders don’t fully understand the tax laws. This means many people are at risk of making mistakes. The new rules aim to fix this problem.
Countries all around the world are making stricter rules. In the
U.S. alone
, people earned
$50 billion
in crypto profits last year. The IRS wants to tax that money. Starting in 2025, brokers must report all your trades. Even small ones will be taxed. If you don’t follow these rules, there could be big fines.
Look at other places like
Europe
. Many countries there are also tightening their crypto tax laws. For example, in
Germany
, if your crypto profits are more than
600 euros
, you will need to pay taxes.
In
Japan
, they’ve already started making big changes. As of
2024
, all crypto transactions must be reported to the government. Even small traders need to follow the rules. Breaking them can lead to heavy penalties.
Don’t forget about the
UK
! They’re creating new crypto tax guidelines, too. In fact,
35%
of UK crypto traders are confused about taxes, according to a
2024 survey
.
The best thing you can do is stay informed. Taxes on crypto are becoming more detailed. Always keep records of every trade. Even if it's a tiny amount, it still matters.
Check the news often for updates. The tax world changes quickly. If you’re ever unsure, ask a professional. They can help you navigate the tricky tax rules and keep you safe from any problems.
So, remember to follow the news, ask for help when needed, and keep all your records organized. Crypto can be fun and exciting, but the tax part is something you can’t ignore!
Expert Opinions and Predictions on Crypto Taxes
As of
September 2024
, experts agree on one thing: crypto taxes are changing fast. Many think stricter rules are coming soon. This is true in the
U.S.
and
Europe
. Governments want to close tax loopholes. Over
50%
of crypto traders are confused. They don’t fully understand the tax rules. This leads to many mistakes.
In the
U.S.
, by
2025
, brokers must report all trades. Even the small ones count. This could mean a big rise in tax filings. The IRS says crypto profits reached
$50 billion
in
2023
. Not reporting these trades could lead to huge fines.
In
Europe
, countries like
Germany
now tax crypto profits over
600 euros
. This means investors need to stay informed. In
Japan
, the government also added strict rules. All trades must be reported. Not following these rules leads to penalties.
A survey says
35%
of
UK
traders don’t understand their tax duties. This confusion is pushing the government to make clearer rules by the end of
2024
.
Experts say it's smart to stay updated. Using crypto tax software helps avoid mistakes. The focus on crypto regulation will keep growing. This makes reporting your trades more important than ever.
Mining Bitcoin in the Cloud with ECOS
If you want to mine Bitcoin without dealing with hardware,
ECOS
offers easy
cloud mining
services. They handle the setup, so you can earn Bitcoin without worrying about equipment or electricity costs. Just remember, mining income is taxable, and ECOS provides detailed reports to help you keep track. It’s a simple way to start mining and stay on top of your crypto taxes!
Frequently Asked Questions
- What happens if I don’t report crypto taxes?
You could face fines or jail time.
- Are crypto gifts taxable?
Yes, if they’re over $17,000.
- How are staking rewards taxed?
They’re taxed as income when received.
- Do I owe taxes if I hold crypto?
No, taxes are owed when you sell or trade.
- Can I deduct crypto losses?
Yes, you can deduct capital losses.
- How do I track my crypto transactions?
Use tools like CoinTracker or TurboTax.
Published Articles
Discover ECOS’s Product 2025
Key Takeaways ECOS’s 2025 product lineup emphasizes flexibility, security, and instant mining activation. October promotions offer up to 20% savings and instant access to used ASICs. Cloud mining contracts now range f...
Global Tariffs Rise — ECOS Slashes Prices
Key Takeaways Global Tariff Crisis: New U.S. tariffs on high-tech imports from China, Malaysia, and Thailand add $1,200–2,000 to the cost of each ASIC miner, driving up equipment expenses and squeezing profit margins...
Spring Promo!
Spring is here, and so are incredible opportunities to enhance your cryptocurrency mining experience! From March 3rd to March 10th , we’re excited to launch our exclusive Spring Promo , offering unbeatable deals tailo...
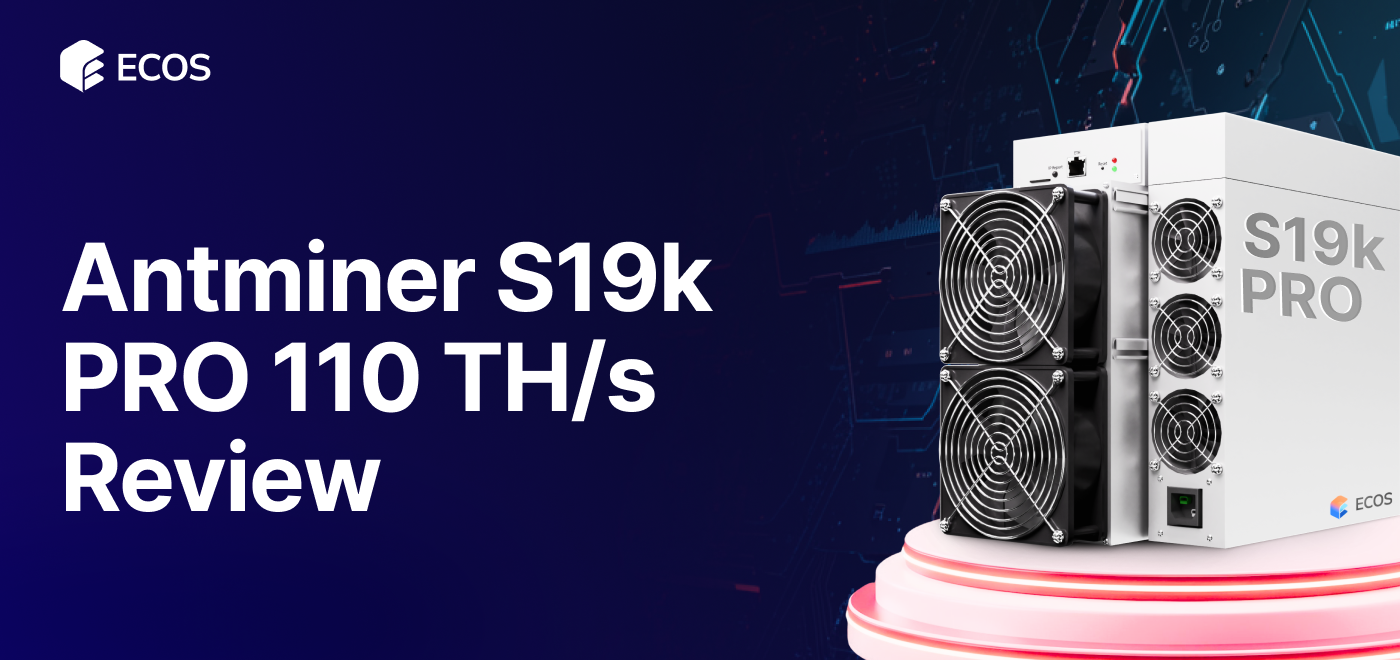
Review of Antminer S19k PRO 110 TH/s: Ultimate Bitcoin Mining Performance
Key Takeaways 110 TH/s hash rate for high-speed mining Energy-efficient at just 23 J/TH Built to work in -20°C to 40°C Easy setup, ready to mine in 7 days Advanced cooling system reduces overheating risks Ideal for sm...
How to Earn Passive Income with Cryptocurrency: Best Strategies for 2025
Key Takeaways Passive income in crypto is residual earnings. Staking and yield farming are top methods. Crypto lending platforms offer high interest rates. Masternodes provide stable rewards and security. Risks includ...
How to Mine Tron (TRX) in 2025: Best Methods, Tools, and Tips for Maximum Rewards
Key Takeaways Tron is a blockchain for decentralized applications. It uses DPoS instead of traditional mining. You can earn TRX through staking and cloud mining. Tron’s low fees make it attractive for miners. Cloud mi...