
Cloud Mining Hedge: How to Protect Your Profits Against Bitcoin Volatility
Introduction
Cloud mining turns computing power into a stream of Bitcoin-denominated revenue, but the value of that stream can change sharply before it reaches a bank account. A contract may produce the expected amount of Bitcoin while delivering fewer dollars, euros, or reais because the market price has fallen. For miners who must cover fixed contract charges, withdrawal fees, taxes, or household expenses, that mismatch can turn an apparently productive month into a weak financial result.
This guide explains how to hedge cloud mining earnings without treating derivatives as a shortcut to profit. The objective is narrower: reduce the damage caused by adverse price moves, preserve enough cash flow to meet obligations, and keep a chosen portion of the upside. Futures, options, staged conversion, reserve policies, and position sizing can all contribute. None removes every risk, and every hedge has a cost. The practical goal is a repeatable process that matches protection to expected production and to the miner's real budget.
Why Cloud Mining Earnings Need Protection
A cloud mining payment is exposed to two moving variables. The first is production: the amount of Bitcoin credited after network difficulty, machine performance, pool results, and contract deductions. The second is price: the exchange value of that Bitcoin when the miner sells or spends it. A decline in either variable reduces cash revenue, and both can deteriorate at the same time.
A hedge is a position designed to gain value when the asset being protected loses value. For a miner expecting Bitcoin, the core exposure is economically similar to being long Bitcoin: revenue benefits from a rising price and suffers from a falling one. Learning how to hedge cloud mining earnings therefore starts with estimating the Bitcoin likely to be received during a defined period. A miner can then offset some of that exposure with a short futures position, a protective put, or a disciplined conversion plan. Protection should be tied to measurable exposure, not to a guess about where the market will go next.
The need for protection depends on how the payout is used. A miner who keeps every satoshi for many years may tolerate monthly volatility. A miner who relies on the payout to cover a subscription, loan payment, electricity allocation, or tax reserve has a much shorter decision horizon. In that case, price stability has operational value even if a hedge reduces the best possible result. Separating the essential portion of revenue from the long-term investment portion makes the policy easier to follow and prevents emotional decisions after a sudden market move.
What Is Hedging in the Cryptocurrency Market?
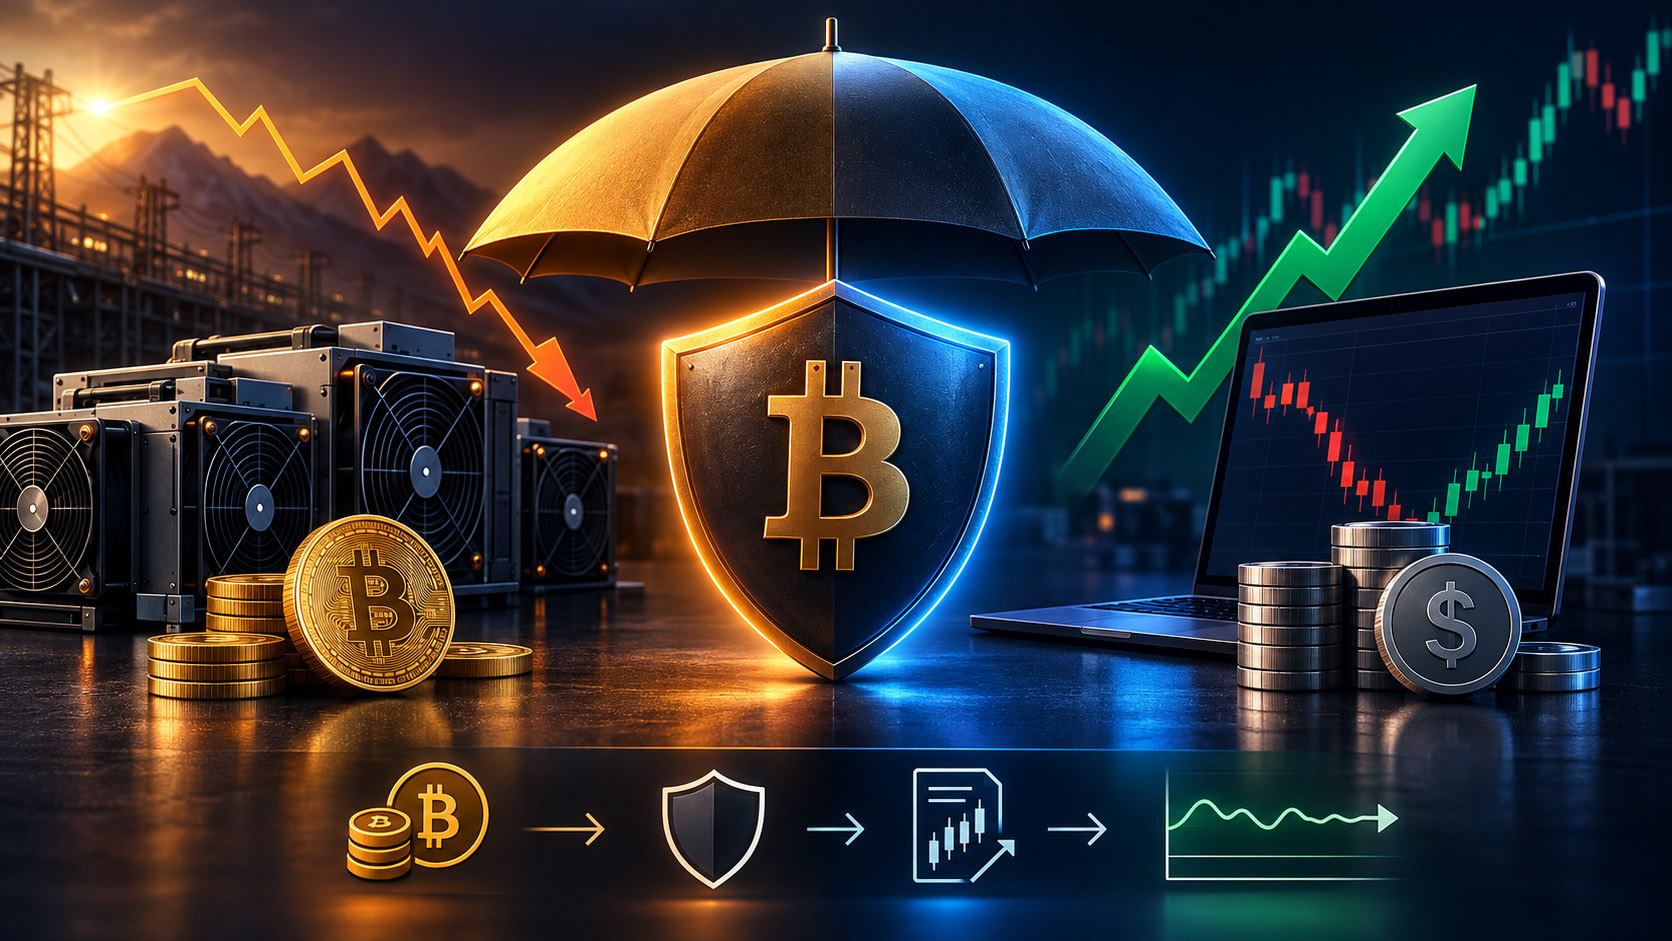
Financial hedging is risk transfer. One position carries the commercial exposure, while another position is selected to offset a specific unfavorable movement. Airlines may hedge fuel, exporters may hedge currencies, and Bitcoin miners may hedge the price of future production. The hedge does not make the underlying activity safe; it changes the shape and timing of potential gains and losses.
A protection strategy works only when the hedge and the exposure respond in sufficiently opposite ways. If a miner expects 0.02 BTC next month and shorts an instrument representing roughly 0.02 BTC, a price decline may reduce the value of mining revenue while producing a gain on the short. The two results will not match perfectly because of fees, basis differences, timing, contract size, margin, and production uncertainty.
Hedging is not a method for increasing profit. A full hedge can also surrender upside when Bitcoin rises. Options can preserve more upside, but the premium is paid whether protection is needed or not. The correct question is not, 'Which trade earns the most?' It is, 'Which risk must be limited, for how long, and at what acceptable cost?'
Main Risks of Cloud Mining Contracts
Bitcoin price risk is the most visible threat. A miner may receive the forecast amount of BTC yet find that its fiat value no longer covers the contract price or operating deductions. The shorter the payback horizon and the greater the reliance on monthly withdrawals, the more important this risk becomes.
Mining difficulty is another source of uncertainty. When more computing power competes for block rewards, the same contracted hashrate may generate less Bitcoin, all else equal. Difficulty can therefore reduce the quantity available to hedge. Overestimating production and hedging the larger amount may leave the miner with a speculative short position.
Fees and operating terms can also change effective revenue. Maintenance charges, electricity assumptions, pool fees, withdrawal thresholds, spreads, and taxes may consume more of the payout than expected. Contract language matters because a hedge on BTC price cannot compensate for every contractual deduction.
Liquidity risk appears when the miner cannot exit a derivative efficiently, cannot post additional margin, or cannot convert mining proceeds when needed. Platform outages, wide spreads, position limits, and counterparty problems can make a sound-looking plan difficult to execute. For that reason, hedging begins with provider and venue due diligence, not with leverage.
How to Hedge Cloud Mining Earnings
The first step in how to hedge cloud mining earnings is to define the exposure window. Use a week, month, or quarter that matches the payout schedule and the bills the revenue must cover. Estimate production conservatively using recent actual payouts rather than the contract's most optimistic projection. Subtract expected fees before sizing the hedge.
Next, choose a hedge ratio. A miner who needs predictable cash flow might protect 60% to 80% of expected net production and leave the rest exposed to price gains. Someone with substantial reserves may hedge only 25% to 50%. Hedging more than expected production creates a new directional bet, so the ratio should include a buffer for lower output.
Finally, document the trigger, instrument, size, expiry, maximum cost, and exit rule before entering the position. Reconcile the hedge when mining payouts arrive. If production changes materially, reduce or add protection deliberately. The process should be boring: estimate, size, execute, monitor, settle, and record.
Using Futures to Hedge Cloud Mining
A futures contract sets an agreed price framework for a later date. A miner can sell, or go short, Bitcoin futures against expected production. If Bitcoin falls, the short position may gain and offset part of the lower value of mined BTC. If Bitcoin rises, the futures position may lose while the mined BTC becomes more valuable.
Futures are efficient because they do not require paying an option premium upfront, but they require margin and active risk control. Bitcoin volatility can produce rapid margin calls even when the commercial hedge makes sense overall. The mining payout may not arrive in time to meet those calls. Contract size is also critical; smaller instruments can allow closer matching for modest cloud mining payouts.
Basis risk remains. A derivative's price may not move exactly with the miner's sale price, and a contract that expires before or after the payout may create a timing gap. Rolling a hedge to a later expiry can add cost. Futures are therefore best suited to users who understand margin, liquidation rules, settlement, basis, and the difference between hedging and leveraged speculation.
Using Options to Hedge Cloud Mining Contracts
A protective put gives its buyer the right, but not the obligation, to sell exposure at a specified strike price before or at expiry, depending on the contract. For a miner, the put can create a floor beneath part of the expected Bitcoin revenue. If the market falls below the protected level, the option may gain value. If Bitcoin rises, the miner can retain much of the upside and let the put expire.
That flexibility has a visible cost: the premium. The miner must decide whether the protection is worth the amount paid. Strike selection changes the balance. A strike closer to the current market normally offers stronger protection but costs more; a lower strike is cheaper but leaves a larger initial decline unprotected. Expiry should cover the expected payout date with enough room for operational delays.
Selling options to finance protection can introduce substantial obligations and should not be treated as a beginner technique. A simple purchased put has a defined premium cost. Complex spreads may reduce that cost, but they also add execution, assignment, and settlement risks.
Futures vs. Options: Which Strategy Should You Choose?
Futures provide a relatively direct offset and can lock in a price more closely, but they may require margin throughout the position and can eliminate much of the upside on the hedged amount. Options cap the buyer's loss at the premium and preserve upside above the strike, but repeated premiums can materially reduce mining returns.
The choice depends on the obligation being protected. If the miner must meet a fixed invoice and can manage margin, futures may offer a tighter match. If the miner wants disaster protection while retaining exposure to a rally, puts may be more suitable. A combined approach is possible: hedge the minimum cash requirement with futures and protect an additional layer with puts. Simplicity should win when the position is small or the user has limited derivatives experience.
Hedging Strategies for Different Miner Profiles
A conservative miner can convert a fixed share of each payout immediately and use a modest put position for the next expected payment. This limits complexity and prioritizes the ability to cover costs. A balanced miner may hedge half of projected production with short-dated futures or puts while leaving the other half unhedged. An aggressive miner may protect only the amount needed for fees and taxes, accepting wider fluctuations on the remainder.
Contract duration also matters. A short contract may need only one or two hedge cycles. A multi-year plan requires repeated estimates because difficulty, fees, payout rates, and personal cash needs will change. No profile should use borrowed money merely to support a hedge. If the margin or premium threatens the household reserve, the hedge is larger or more complex than the budget can support.
How to Calculate How Much Bitcoin to Protect
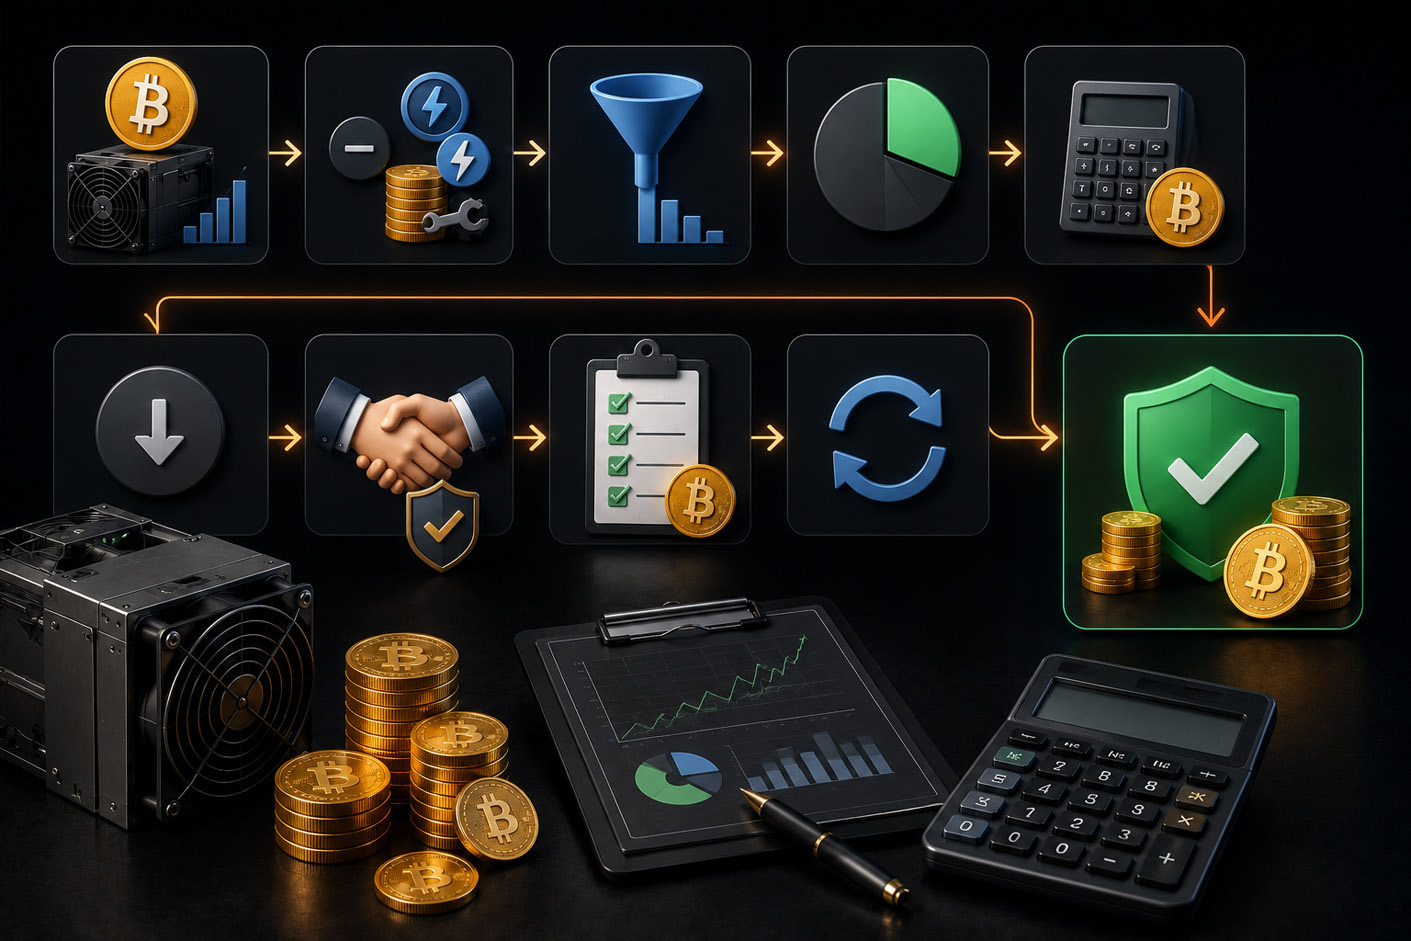
Start with expected gross BTC for the hedge period, then subtract variable deductions paid in BTC. Apply a conservative production factor, such as 80% to 90% of the recent average, when output is uncertain. Multiply the result by the desired hedge ratio. For example, expected net production of 0.02 BTC with an 80% confidence adjustment and a 60% hedge ratio produces a target exposure of 0.0096 BTC.
Round down to the nearest practical contract increment. Then compare the protected fiat value with the actual obligation. If the purpose is to secure a $500 bill, do not automatically hedge the entire payout. This calculation makes how to hedge cloud mining earnings a budgeting exercise rather than a market prediction. Review the estimate whenever actual payouts deviate materially from the plan.
Tools for Monitoring Cloud Mining Risk
A simple risk dashboard should track expected BTC, actual BTC, average sale price, contract deductions, hedge notional, hedge ratio, expiry, margin balance, option premium, and the fiat amount that must be protected. Network difficulty, hashrate trends, and estimated hashprice can provide context, but actual account payouts remain the best starting point for personal exposure.
Set alerts for price thresholds, margin utilization, expiry dates, and production shortfalls. Keep exchange and provider records separate so performance can be reconciled. A hedge that appears profitable may merely offset a larger decline in mining revenue; both sides must be measured together. Avoid relying on a single platform for data, execution, and custody when a practical alternative exists.
A monthly review should answer five questions: Did production match the estimate? Did the hedge size remain below actual net output? How much did fees, premiums, funding, or roll costs reduce the benefit? Was enough cash available for margin and normal expenses? Did the policy reduce cash-flow volatility as intended? These records turn how to hedge cloud mining earnings into a process that can be improved. Without them, a miner may remember the winning derivative trade and overlook the decline it was meant to offset, or blame the hedge for a lost rally even though it protected an essential payment.
The Future of Hedging for Bitcoin Miners
Risk tools are becoming more granular. Smaller contract sizes, more frequent expiries, and products linked to Bitcoin volatility can allow closer matching than older one-size-fits-all contracts. Specialized instruments tied to mining economics may also improve the ability to hedge hashprice rather than BTC price alone.
Better products do not remove operational discipline. Cloud miners will still need to estimate production, understand settlement, monitor counterparties, and avoid excess leverage. The strongest long-term improvement may be cultural: treating mined Bitcoin as business revenue with a risk policy, rather than as a lottery ticket whose value is checked only after a market move.
Key Takeaways
- Cloud mining earnings combine production risk and Bitcoin price risk; one hedge cannot remove both.
- A hedge should be sized against conservative expected net production and a real cash obligation.
- Short futures can offset price declines but introduce margin, basis, and liquidation risks.
- Protective puts preserve more upside, although premiums reduce net returns.
- Partial hedging often gives a more practical balance between stability and participation in a rally.
- The plan must be reviewed when payouts, fees, difficulty, or personal cash needs change.
Expert Perspective
The core principle is consistent with guidance from regulated derivatives authorities: futures and options are designed to help holders manage price volatility, but leveraged positions remain high-risk. CME Group educational material similarly shows that a put on Micro Bitcoin futures can protect part of a physical Bitcoin position while preserving potential upside. Applied to cloud mining, the lesson is straightforward: the derivative should be smaller than or equal to a defensible estimate of expected production, and the miner must understand the instrument before using it.
That expert perspective also highlights an important distinction between commercial hedging and speculation. A commercial hedge begins with an existing or highly probable exposure and is reduced when that exposure disappears. A speculative trade begins with a view about price. Cloud miners should be able to show, in their own records, which expected payout each derivative protects. If a contract is renewed, production falls, or the payout is delayed, the hedge should be reconsidered rather than left open simply because the trader hopes it will become profitable.
Conclusion
Knowing how to hedge cloud mining earnings means deciding which cash flow matters most, estimating the Bitcoin that will realistically arrive, and buying only enough protection to support that objective. Futures can create a tighter offset; options can establish a floor while preserving upside; staged conversion and reserves can reduce the amount that needs a derivative at all. The most resilient plan is conservative, documented, and reviewed against actual payouts. Hedging cannot guarantee profitability, but it can make an uncertain revenue stream easier to manage.
FAQ
- What does hedging cloud mining earnings mean?
It means taking a position or following a conversion policy intended to reduce the loss caused by an unfavorable change in Bitcoin's price.
- Can a hedge guarantee cloud mining profit?
No. It can reduce a defined price risk, but it cannot eliminate lower production, contract fees, counterparty failure, taxes, or execution costs.
- How often should a hedge be adjusted?
Review it when payouts arrive and whenever expected production, price exposure, obligations, or contract terms change materially.
- Are futures or options better for beginners?
Purchased puts have a defined premium cost, while futures involve margin and possible liquidation. Neither is appropriate without understanding the instrument and venue.
- Should every miner hedge 100% of expected Bitcoin?
Usually not. Forecast error can turn an oversized hedge into a speculative short. Many miners prefer partial protection based on required cash flow.
- What is the simplest alternative to derivatives?
Converting a fixed share of each payout and maintaining a fiat reserve can reduce volatility without futures or options.
Published Articles
Buy or Mine Bitcoin: Cloud Mining vs Spot Purchase Compared
This bitcoin mining vs spot purchase return comparison examines costs, BTC accumulation, liquidity, risks, and break-even points for investors.
Bitcoin Cloud Mining Profitability Forecast
Build a cloud mining profitability forecast using Bitcoin output, difficulty, fees, uptime, and price scenarios to estimate net returns and payback.
How to Add Cloud Mining to a Crypto Portfolio
Learn how to add cloud mining to a crypto portfolio, choose a sensible allocation, track net returns, and control provider and liquidity risk.
How the Dollar and Exchange Rates Affect Cloud Mining Profitability
Understand the dollar impact on cloud mining profitability through Bitcoin prices, contract costs, exchange rates, fees, and local-currency returns.
Long-Term Cloud Mining Strategy: Planning Bitcoin Accumulation Over Several Years
Build a long-term cloud mining strategy around contract costs, mining difficulty, payout records, risk limits, and realistic Bitcoin accumulation goals.
Passive Income with Bitcoin Cloud Mining: Is Mining a Viable Long-Term Strategy?
Explore passive income with bitcoin cloud mining, including contract mechanics, changing returns, provider risk, and the case for a long-term strategy.