
Long-Term Cloud Mining Strategy: Planning Bitcoin Accumulation Over Several Years
Introduction
Cloud mining can turn a single contract purchase into a stream of Bitcoin payouts without putting an ASIC miner in the customer’s home. The provider supplies the machines, electricity, cooling, repairs, and pool connection. The customer buys a defined amount of hashrate and receives the resulting share of mining revenue after fees. That arrangement removes much of the operational work, but it does not make the outcome predictable.
A contract may run for several years while Bitcoin’s price, network difficulty, transaction fees, energy costs, and mining hardware all change. The amount of Bitcoin produced by a fixed unit of hashrate usually declines when more computing power joins the network. A higher Bitcoin price can improve the value of payouts, yet it does not reverse the decline in coin production. These variables need to be tracked separately.
A long-term cloud mining strategy therefore needs a budget, a method for judging contracts, and rules for responding when the original assumptions stop holding. Its purpose is to accumulate Bitcoin at an acceptable total cost while keeping provider and contract risk within limits the investor can afford. It cannot guarantee a profit or a specific quantity of Bitcoin.
What a Long Term Mining Plan Actually Buys
A cloud-mining customer normally buys contractual access to computing power rather than ownership of a named machine. The agreement states the hashrate, activation date, term, maintenance charge, payout method, minimum withdrawal amount, and conditions under which service can be suspended. Some products charge all costs upfront. Others deduct electricity and service expenses from daily mining revenue.
This distinction matters over a long period. A contract described as lasting three or five years may end earlier if daily revenue no longer covers maintenance charges. The provider may also reserve the right to move equipment, substitute hardware, change pools, or pause service after an outage. An investor should know which rights are fixed and which remain at the provider’s discretion.
Bitcoin accumulation is the output of this service. It is not an interest payment on the purchase price. Each payout depends on the customer’s share of pool production, the block subsidy, transaction fees, uptime, and deductions. The contract should make that calculation traceable from gross mining revenue to the amount credited to the account.
Why Several Years Change the Economics
Bitcoin mining is competitive. The protocol adjusts difficulty so blocks continue to arrive at roughly the intended pace as network hashrate changes. When total network computing power rises, a fixed cloud-mining allocation represents a smaller share of the competition. The same contract can consequently produce fewer bitcoin over time even when its machines run normally.
The block subsidy also falls at scheduled halving events. Transaction fees may offset part of that reduction in some periods, but fee revenue varies with demand for block space. A plan that crosses a halving should model the lower subsidy directly rather than treating the first month’s production as a constant annual rate.
Hardware ages in economic terms as newer ASIC models deliver more hashrate per unit of electricity. Older machines can remain technically functional while becoming too expensive to operate. Because the provider decides which equipment supports the contract, the agreement should explain whether hardware may be upgraded and whether an upgrade changes the customer’s fees or hashrate.
Set an Accumulation Goal Before Buying
Start with the amount of capital that can remain at risk for the full contract term. Cloud-mining payments may be difficult or impossible to recover after activation, and a secondary market may not exist. Money reserved for near-term expenses or emergencies does not belong in a multi-year mining contract.
Next, define the goal in Bitcoin rather than only in dollars. An investor might aim to build a modest long-term position, add mining payouts to an existing purchase plan, or test whether cloud mining offers a reasonable acquisition cost. A target creates a basis for measuring progress, although the final quantity remains uncertain.
The long-term cloud mining strategy should also state what would make it unsuccessful. Examples include a net acquisition cost consistently above the investor’s alternative purchase cost, missing payout records, unexplained fee changes, or excessive exposure to one provider. Writing these limits before investing reduces the temptation to redefine success after conditions deteriorate.
Build a Multi Year Budget
A long-term cloud mining strategy needs to separate the upfront contract payment from ongoing deductions. The first is committed capital. Maintenance charges, electricity fees, pool fees, withdrawal fees, and currency-conversion costs reduce the Bitcoin ultimately received. A low contract price can be misleading when variable deductions absorb a large portion of production.
Keep a cash reserve outside the contract. It can cover taxes, wallet transaction costs, or a planned purchase of Bitcoin during a period when mining output falls. The reserve should not be treated as money available to rescue a contract whose economics no longer work.
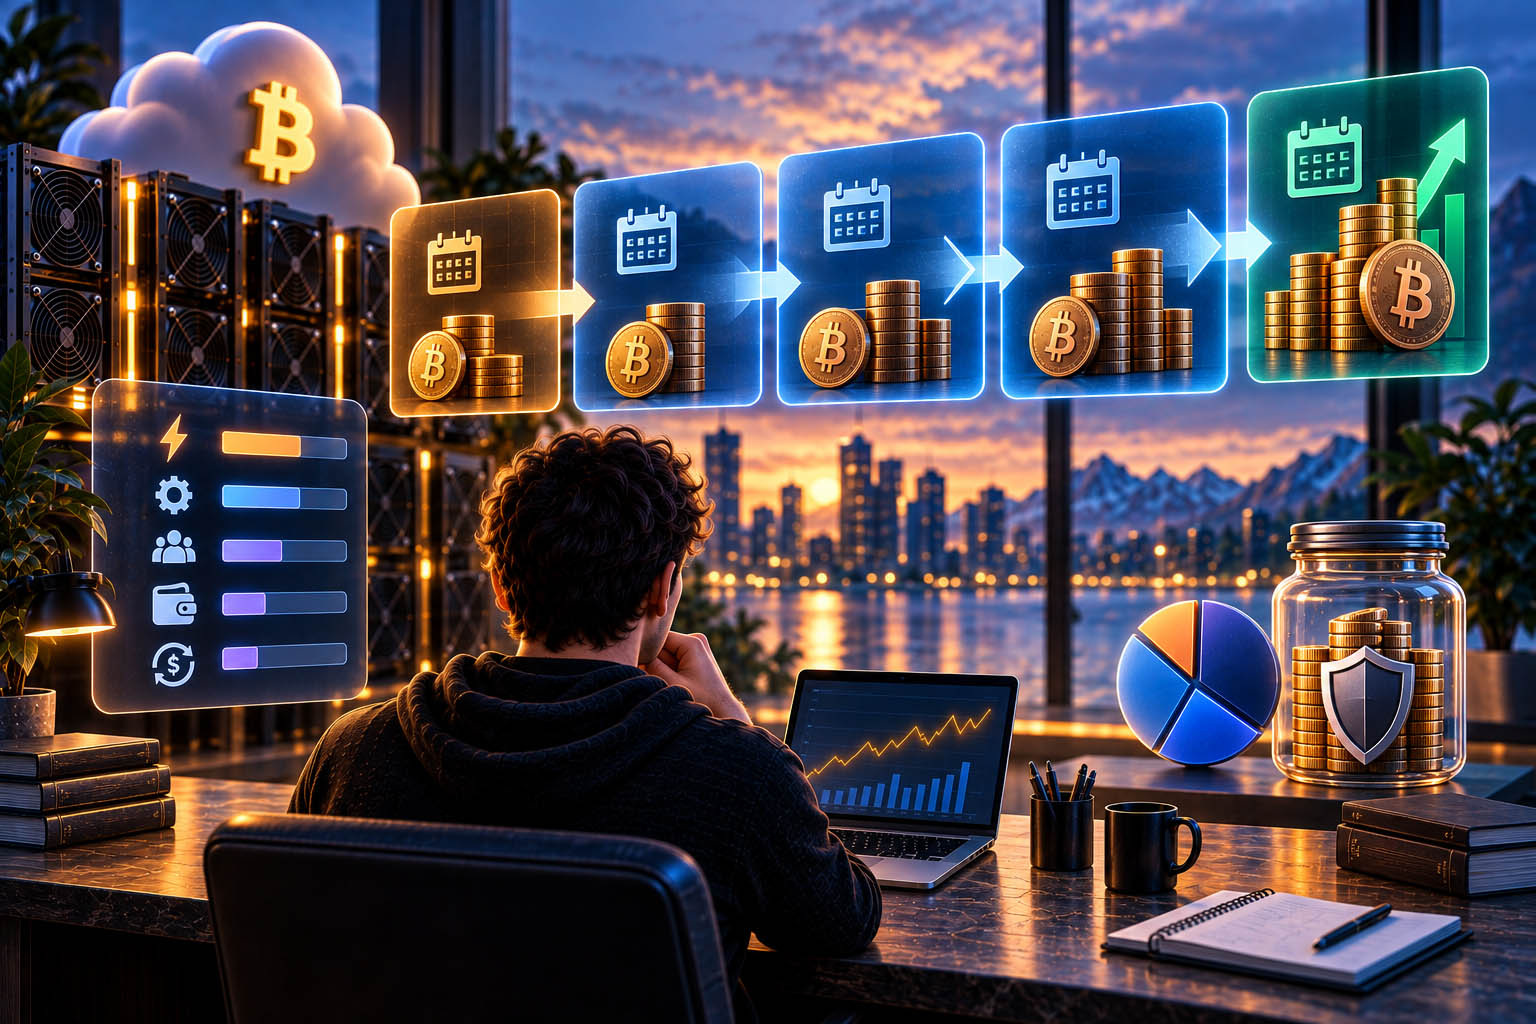
Avoid committing the entire multi-year budget on one date. Staged purchases let the investor observe real payouts and provider behavior before increasing exposure. They also reduce dependence on the market conditions and contract pricing available at a single moment.
A Simple Allocation Schedule
One practical approach is to divide the intended budget into several tranches. The first tranche funds a small contract that can be monitored through multiple payout cycles. Later tranches remain optional and are deployed only if the provider’s records, actual deductions, and contract performance match the terms.
Set the total capital limit for the strategy before evaluating offers.
Reserve only a portion for the first contract or activation period.
Hold the remaining capital in a liquid form while results are reviewed.
Require a fresh comparison with direct Bitcoin purchases before each addition.
Stop adding capital when a stated risk limit or review trigger is reached.
This schedule does not eliminate timing risk. It simply gives the investor more evidence before each commitment and prevents one early decision from consuming the whole budget.
Model Bitcoin Production Conservatively
A forecast should begin with the contract’s hashrate and a clearly dated estimate of network difficulty. It should then account for the pool payout method, expected uptime, block subsidy, transaction-fee assumptions, and every contractual deduction. The model is useful only when its inputs can be updated.
Do not extend the first payout across the full contract term. Early production may reflect a different difficulty level, a temporary fee environment, or a partial billing period. Use several observations and compare them with independently calculated expectations. A persistent gap needs an explanation.
Run at least three scenarios. A base case can use moderate assumptions drawn from current contract terms. A difficult case should combine rising network difficulty, lower Bitcoin prices, and full maintenance charges. A severe case should test whether the contract could stop producing net payouts for an extended period or terminate under an unprofitability clause.
Measure Cost Per Bitcoin
For accumulation, the central metric is total net cost per bitcoin received. Add the contract price and all related out-of-pocket costs, then divide by the Bitcoin withdrawn to the investor’s wallet. Recalculate the figure over time rather than waiting until the contract ends.
This metric allows a fairer comparison with buying Bitcoin directly. Direct purchases have trading and withdrawal fees, while cloud mining has contract, operating, and provider risks. If mining produces Bitcoin at a higher cost, the investor needs a clear reason to continue, such as diversification of acquisition timing or a credible expectation that later production will change the comparison.
Account for Halvings and Difficulty Growth
A halving is known in advance at the protocol level, although its exact calendar date depends on block production. The subsidy paid to miners falls by half, so contracts that span the event need a lower post-halving production assumption. A price increase is possible, but it should not be inserted into the model as compensation for the subsidy cut.
Difficulty is harder to forecast. New mining capacity, efficient hardware, energy conditions, and operator decisions can all affect network hashrate. Instead of choosing one annual growth rate and treating it as certain, test a range. The downside case should be uncomfortable enough to expose whether the contract relies on unusually favorable conditions.
Review production after each difficulty adjustment and compare actual Bitcoin earned per unit of hashrate with the plan. Small differences are normal because pools use different payout methods and experience variance. A widening unexplained difference may point to downtime, changed fees, or reporting problems.
Evaluate the Provider as an Operating Business
A multi-year contract is only as durable as the business that must perform it. The provider should identify its legal entity, management, service locations, and customer-support channels. Facility evidence, equipment information, and a coherent explanation of energy sourcing help establish whether real mining operations exist.
Look for terms that describe downtime, repairs, force majeure, termination, refunds, and customer complaints. Read them before paying. Broad discretion to suspend service without reporting the cause transfers substantial risk to the customer, especially when the purchase price is non-refundable.
Payout records are another source of evidence. The account history should show gross production, deductions, net credits, and withdrawals. Compare credited amounts with pool or network conditions when possible. Screenshots supplied by promoters are less useful than records from the customer’s own account and transactions visible in the customer’s wallet.
Warning Signs
Guaranteed returns or a fixed Bitcoin yield despite changing network conditions.
Anonymous ownership, unverifiable facilities, or inconsistent company information.
Pressure to deposit quickly or rewards focused mainly on recruiting new customers.
Fees, payout formulas, or termination rules that are missing or difficult to obtain.
Withdrawal delays that receive vague explanations or require new deposits.
Any one issue deserves investigation. Several appearing together are a strong reason to walk away, regardless of how attractive the projected return looks.
Control Contract and Counterparty Risk
Provider diversification can limit the damage from one company failing, but it should follow due diligence rather than replace it. Splitting money among several opaque services creates several weak exposures. A smaller number of well-understood contracts may be easier to monitor.
Contract duration also affects risk. Longer terms provide more time for Bitcoin accumulation, but they expose the investor to more difficulty adjustments, hardware changes, regulatory developments, and business decisions. Shorter terms can offer earlier reassessment, though their price per unit of hashrate may be higher.
Check whether the contract can be transferred, cancelled, or sold. Many cannot. If the only exit is to wait for payouts or accept termination, position size becomes the main risk control. Assume liquidity is poor unless the agreement establishes a practical, enforceable exit process.
Decide How Payouts Will Be Handled
Payouts left on a provider’s platform remain exposed to that platform. Withdraw Bitcoin to a wallet controlled by the investor when balances and network fees make the transaction sensible. Confirm the destination address carefully and protect wallet recovery information offline.
A plan should specify whether mining proceeds will be held, sold to cover costs or taxes, or used to buy more hashrate. Reinvestment compounds exposure to the same provider and mining economics. It should be a new investment decision supported by current evidence, not an automatic setting chosen at the start.
Record the date, gross production, deductions, net payout, withdrawal fee, and amount received in the wallet. Consistent records make tax reporting easier and reveal when performance departs from the contract or the original model.
Review the Plan on a Fixed Schedule
A long-term cloud mining strategy needs regular reviews because the contract and the mining environment evolve at different speeds. A monthly check may be enough for payouts and deductions. A broader quarterly review can revisit difficulty trends, provider disclosures, contract economics, and progress toward the accumulation goal.
Event-based reviews are equally important. Recalculate the plan after a halving, a material fee change, repeated downtime, a delayed withdrawal, or an amendment to the terms. Personal circumstances can also trigger a review if the investor’s liquidity needs or tolerance for loss changes.
Use the same decision rules each time. Continue when records remain credible and the downside stays within the stated limit. Pause new purchases when evidence is incomplete. Exit where the contract permits if the provider breaches material terms or the strategy no longer serves the investor’s goal.
Review Checklist
Reconcile credited Bitcoin with the provider’s production and fee records.
Update difficulty, subsidy, uptime, and transaction-fee assumptions.
Calculate cumulative net cost per bitcoin received in the wallet.
Check provider announcements, legal details, and changes to contract terms.
Compare the result with direct Bitcoin purchases made on the same schedule.
Confirm that total exposure remains within the original capital limit.
Compare Cloud Mining with Direct Purchases
Buying Bitcoin directly is simpler. The investor knows the amount acquired at the time of purchase and can move it to self-custody after the trade. The main variables are price, trading fees, withdrawal costs, custody, and tax treatment. There is no dependence on future machine uptime or provider operating decisions.
Cloud mining spreads acquisition across future production and may appeal to investors who want exposure to mining economics. It adds contractual, operational, and counterparty risk. The eventual quantity of Bitcoin is unknown, and the investor may pay more per bitcoin than through direct purchases.
The comparison should use the same capital schedule. If a contract requires an upfront payment, compare it with buying Bitcoin upfront and with buying at regular intervals. Count all costs and use Bitcoin actually received in a personal wallet, not a dashboard balance or a gross production estimate.
Who May Find the Strategy Suitable
A long-term cloud mining strategy may suit an investor who understands that the product is a high-risk service contract, can leave capital committed, and is willing to monitor detailed records. It may also fit someone who wants mining exposure without operating noisy, heat-producing equipment or arranging electricity and repairs.
It is a poor fit for anyone who needs guaranteed income, immediate access to capital, or a fixed quantity of Bitcoin. Beginners who cannot yet verify wallet transactions, read fee formulas, or distinguish hashrate from projected revenue should learn those basics before buying a long contract.
The position should remain small enough that total loss would not disturb essential finances. Cloud mining is not a substitute for emergency savings, diversified long-term investing, or secure custody practices.
Key Takeaways
A multi-year contract buys access to hashrate, not a guaranteed stream of Bitcoin.
Difficulty growth, halvings, fees, uptime, and provider decisions shape actual production.
Staged commitments provide evidence before more capital becomes locked in.
Net cost per bitcoin is more useful than an advertised annual return.
Direct Bitcoin purchases provide an important benchmark at every review.
Clear stop rules matter because many cloud-mining contracts have little liquidity.
Conclusion
A long-term cloud mining strategy can support gradual Bitcoin accumulation when the contract is transparent, the provider is credible, and the investor monitors actual production. The plan should begin with a firm capital limit and conservative assumptions about difficulty, halvings, fees, and uptime. Payouts need to be reconciled and moved to a secure wallet on a sensible schedule.
Treat each new contract or reinvestment as a fresh decision. Compare the net cost of mined Bitcoin with direct purchases, update the downside case, and stop adding capital when the evidence weakens. A disciplined process cannot remove mining risk, but it can keep that risk visible and bounded.
FAQ
- Can cloud mining guarantee a specific amount of Bitcoin over several years?
No. Production changes with network difficulty, the block subsidy, transaction fees, pool performance, uptime, deductions, and the provider’s continued operation.
- How often should a long-term cloud-mining plan be reviewed?
Check payouts monthly, review the full plan quarterly, and recalculate after a halving, fee change, outage, or delayed withdrawal.
- Is a five-year contract safer than several shorter contracts?
Not automatically. A longer term increases exposure to provider, hardware, difficulty, and rule changes. Shorter contracts allow earlier reassessment but may carry higher pricing.
- Should mining proceeds be reinvested automatically?
Automatic reinvestment increases exposure without a fresh review. Reinvest only after comparing current terms, provider performance, and direct Bitcoin purchases.
- Which metric best tracks a Bitcoin accumulation strategy?
Track total net cost per bitcoin received in a wallet you control. Include the contract price, fees, and other direct costs.
- Can the entire cloud-mining investment be lost?
Yes. Provider failure, contract termination, unfavorable mining economics, fraud, or legal restrictions can reduce payouts or stop them completely.
Published Articles
How to Add Cloud Mining to a Crypto Portfolio
Learn how to add cloud mining to a crypto portfolio, choose a sensible allocation, track net returns, and control provider and liquidity risk.
Passive Income with Bitcoin Cloud Mining: Is Mining a Viable Long-Term Strategy?
Explore passive income with bitcoin cloud mining, including contract mechanics, changing returns, provider risk, and the case for a long-term strategy.
Ideal Cloud Mining Investor Profile: Who Is This Strategy For?
Explore the ideal cloud mining investor profile, including suitable goals, time horizon, crypto knowledge, risk tolerance, and reasons to avoid this strategy.
Best Cloud Mining Platforms in Russia and the CIS
Compare the best cloud mining platforms for Russia and the CIS by fees, contract terms, payouts, regional access, and operating transparency.
Best Cloud Mining Platforms Compared
Compare the best cloud mining platforms by contracts, fees, payouts, security, operating evidence, and the risks that matter before you deposit funds.
Bitcoin Mining ROI: How to Calculate Profitability and Forecast
Introduction The Antminer S21 XP consumes 3.5 kW per hour and mines around 0.00014 BTC per day at current network difficulty. With electricity at $0.07 per kWh and Bitcoin at $100,000, that produces roughly $14 in rev...