
Crypto Savings Accounts and Staking: Ways to Earn Income from Cryptocurrency
Introduction
Holding cryptocurrency does not automatically produce income. A balance grows only when its market price rises, more units are added, or both occur. Crypto savings accounts and staking offer ways to increase the number of tokens held, but they generate rewards through different mechanisms and expose the owner to different failures.
A savings account usually places a company between the customer and the underlying activity. The provider may lend assets, use them as collateral, deploy them in DeFi, or support another revenue strategy. Native staking connects eligible tokens to the consensus process of a proof-of-stake blockchain. Custodial staking can place a company in that path as well.
Anyone planning to earn interest on cryptocurrency should begin with the source of the return. The displayed annual rate is only a starting point. Custody, borrower quality, validator performance, token inflation, lock-up terms, fees, taxes, and price volatility decide what the holder ultimately receives and whether the funds remain accessible.
Ways to Generate Income from Cryptocurrency
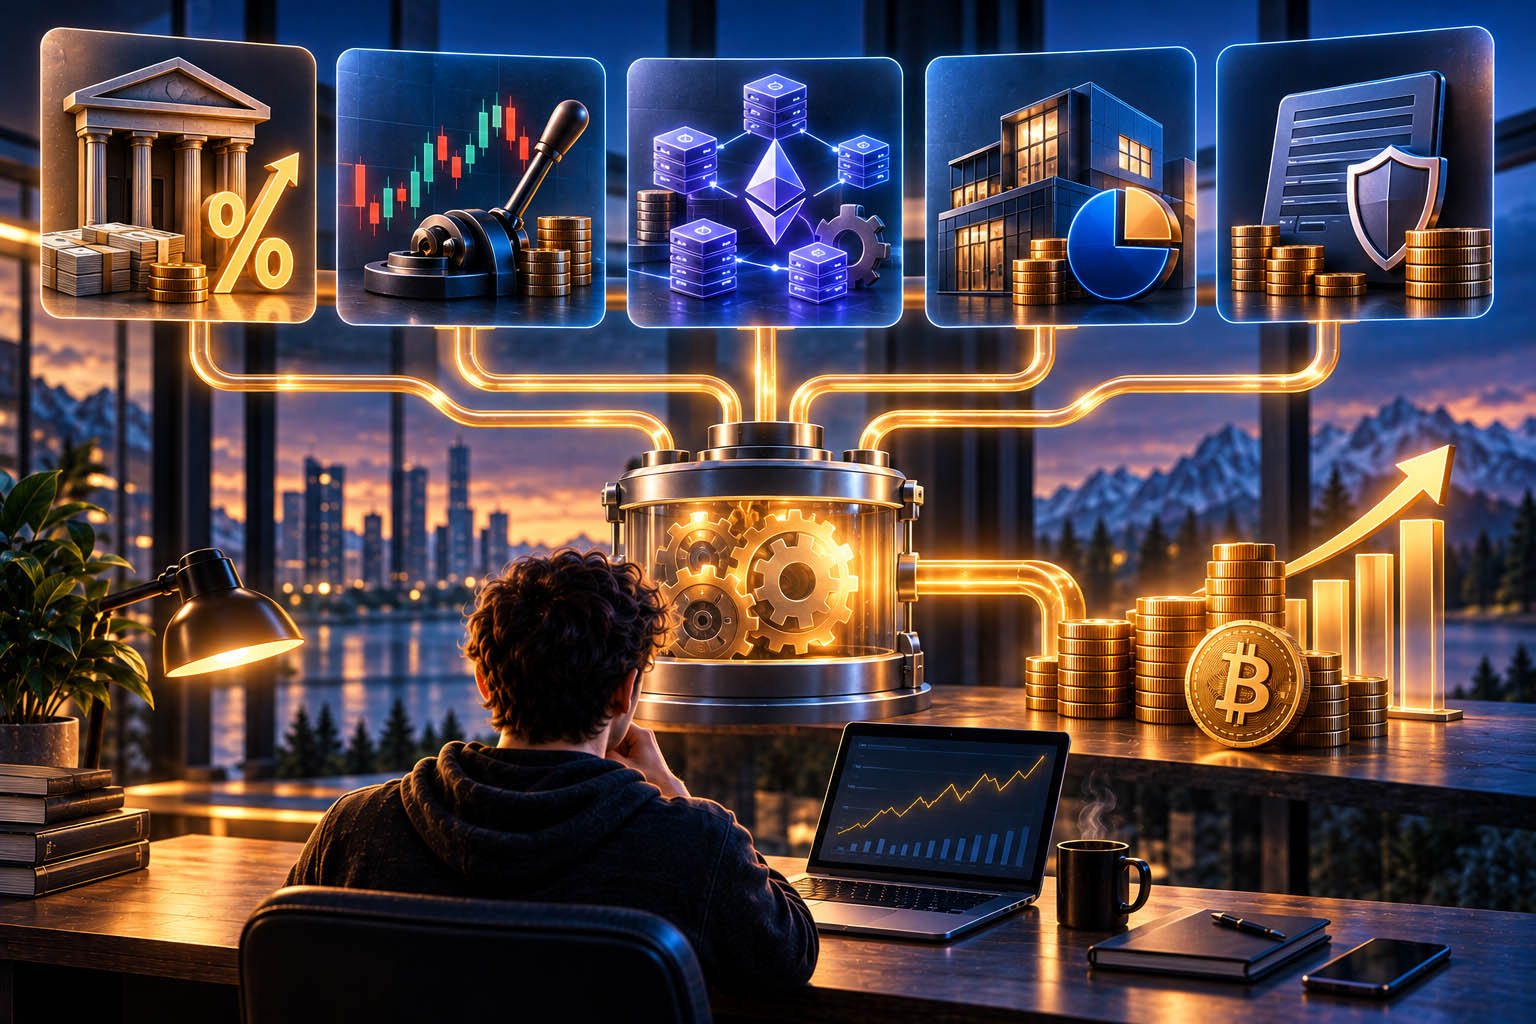
Crypto income can come from lending, protocol rewards, liquidity provision, token incentives, or business revenue shared by a platform. These sources are not interchangeable. Lending depends on borrowers and collateral. Staking depends on a blockchain and its validators. Liquidity provision depends on trading activity and the prices of assets in a pool.
Before depositing, ask what happens to the coins after they leave the wallet. Identify who controls the private keys, which contract or institution holds the assets, how the return is produced, who absorbs losses, and how withdrawal requests are handled. A provider that cannot describe the mechanism clearly has not supplied enough information for a risk decision.
Rates should be compared after every deduction and in the asset actually received. A reward paid in a volatile token may create a very different result from interest paid in a stable-value asset. Measure the token increase and its fiat value separately so a price rally does not hide weak income generation.
What Are Crypto Savings Accounts?
A crypto savings account is a platform product that accepts digital assets and credits a stated yield. Unlike a bank deposit, the balance may not have the same legal protections, insurance, or regulatory treatment as ordinary savings. The exact arrangement depends on the provider and jurisdiction, so the product’s name says little about the underlying risk.
Some accounts are flexible and allow withdrawal on demand. Others require a fixed term or offer a higher rate for accepting notice periods. The provider can set supported assets, minimum balances, reward schedules, eligibility, and withdrawal limits. These terms can change, especially when market liquidity or regulation changes.
The customer generally gives up direct control of the deposited coins. The platform records the balance and promises repayment according to its terms. That creates counterparty risk: even if the underlying cryptocurrency works normally, insolvency, account restrictions, operational failures, or a security incident can interrupt access.
How Crypto Savings Work
After a deposit, the provider allocates assets according to its business model. It may lend them to institutions or traders, supply liquidity, place collateral in another market, or use a mixture of strategies. Income from those activities funds the customer rate after the provider deducts its margin and operating costs.
The account interface may show a simple APY while the asset moves through several counterparties and contracts. Each additional layer can introduce credit, custody, liquidity, smart-contract, or legal risk. Customers should look for an explanation of asset use, collateral practices, risk limits, reserves, and the circumstances in which withdrawals can be delayed.
Rewards may accrue daily, weekly, or monthly. Some platforms add them to the interest-bearing balance automatically, while others require a claim or place them in a separate wallet. Check whether the quoted rate assumes compounding, whether rewards are paid in the deposited asset, and which fees apply when funds leave the platform.
Where the Yield Comes From
A sustainable yield needs an identifiable source of revenue. Borrowers may pay interest for access to capital. Traders may pay fees for leverage or liquidity. A DeFi protocol may distribute transaction revenue or temporary token incentives. A platform may share part of its own business income. Each source responds differently when demand weakens.
High rates often indicate that the provider needs capital, is offering a temporary subsidy, or is taking more risk. The rate alone does not reveal which explanation applies. Review the borrower or strategy, collateral quality, liquidation process, duration mismatch, and whether rewards rely on issuing a token whose market value may fall.
If the provider promises a fixed customer rate while earning a variable return, someone must absorb the difference when revenue falls. That party may be the company, an insurance fund, reserves, or ultimately the customer through changed terms and withdrawal restrictions. The agreement should explain this allocation.
Fixed and Variable Returns
A fixed rate usually applies for a stated period and under specified conditions. It does not make the position risk-free. The provider can still fail, the deposited asset can fall, and early withdrawal may be unavailable or expensive. Confirm whether “fixed” describes the percentage, the term, or both.
Variable rates adjust with market demand, protocol activity, or platform policy. They may rise during periods of heavy borrowing and fall when demand contracts. Use a range rather than the current rate in any forecast, and review the account whenever the provider changes its methodology.
High-Interest Crypto Savings Accounts: What Determines Yield?
The offered yield reflects the value of the deposited asset to the provider and the risk of the strategy used. Scarce liquidity, high borrowing demand, leverage, or promotional spending can lift a rate. Strong competition can do the same for a limited period. None of these conditions is guaranteed to persist.
Rates also depend on term, withdrawal access, account size, customer location, and whether the reward is paid in the deposited coin or a platform token. Tiered accounts may advertise a high percentage that applies only to a small balance. Read the calculation rules before projecting income across the full deposit.
Type of Cryptocurrency
Stable-value assets often show lending rates because borrowers want dollar-like liquidity. Their lower price volatility does not eliminate issuer, reserve, depegging, custody, or platform risk. A stablecoin account can lose value or access even when the quoted interest was paid exactly as described.
Bitcoin and other non-staking assets can earn through lending or platform strategies, not native proof-of-stake rewards. Proof-of-stake tokens may earn through validators, lending, or both, depending on the product. Always separate the asset’s native mechanism from the provider’s chosen use.
Market Conditions
Borrowing demand, available liquidity, market volatility, collateral values, and competition among providers all influence savings rates. During stressed markets, rates can rise because capital is scarce, while withdrawal and counterparty risk may also be increasing. A higher yield does not make a deteriorating market safer.
The deposited asset’s price can dominate the interest earned. A 5% increase in token balance offers little protection against a 40% decline in market value. Build separate scenarios for yield and price instead of combining optimistic assumptions into one projection.
Platform Terms
Read the terms for ownership, custody, reuse of assets, collateral, withdrawals, reward changes, account freezes, supported jurisdictions, and dispute resolution. Look for language that allows the provider to lend, pledge, or transfer customer assets. These permissions determine how many parties stand between the customer and repayment.
Advertising pages may summarize a product more simply than the legal agreement. Save the version accepted at deposit and keep statements, notices, and withdrawal records. If the provider changes a material rule, compare the new arrangement with the reason the account was opened.
Deposit Period
Flexible accounts offer faster access but may pay less. Fixed-term products can offer a higher rate in exchange for restricted withdrawals. Notice accounts sit between the two, requiring a request several days or weeks before release. The correct choice depends on when the funds might be needed.
Do not lock emergency money or assets reserved for a known expense. Market stress can extend processing times even where normal withdrawals are described as quick. Test the withdrawal process with a small amount and keep enough liquid assets outside the platform for fees and near-term needs.
What Is Crypto Staking?
Staking commits eligible tokens to the security and operation of a proof-of-stake blockchain. A validator places the native asset at risk and runs software that participates in consensus. Other holders can often delegate their voting weight to a validator while keeping the position visible through the network’s wallet or explorer.
The protocol distributes rewards for correct participation. The amount depends on network issuance, transaction-related income, total stake, validator performance, and commission. A quoted annual rate can change during the holding period and should be evaluated alongside token inflation and price risk.
Some services call unrelated reward products staking. If the provider cannot identify the chain, validator, stake transaction, and protocol rule that generates rewards, evaluate the product as a custodial yield account. The label does not create the protections of native staking.
How Proof of Stake Works
Proof-of-stake networks select validators to propose blocks and attest to valid activity. The algorithm differs by chain, but validators support their behavior with economic collateral. Reliable participation earns rewards. Detectable violations can bring penalties or slashing, which destroys part of the stake.
This design secures the network without the energy-intensive hash competition used by proof-of-work mining. Validators still need stable infrastructure, secure keys, current software, monitoring, and recovery procedures. Delegation removes the server work for the holder but leaves validator selection and network risk.
The Role of Validators
Validators keep consensus software online, propose blocks when selected, and vote on blocks from other participants. Long outages reduce earnings and can bring penalties. Conflicting signatures or other consensus violations can trigger slashing on networks that use it.
Delegators should review uptime, commission policy, operating history, infrastructure diversity, and concentration. A low commission is useful only if the validator performs reliably. Very large operators can also concentrate voting power and create correlated risk for the network.
Sources of Rewards
Staking rewards can include newly issued tokens and a share of transaction-related fees. The mix varies by protocol. When more of the token supply is staked, the reward per unit may fall. When activity or fee income changes, the rate can change again.
Evaluate net rewards after validator commission, provider fees, missed duties, taxes, and inflation. The holder’s token count may rise while purchasing power falls. Track both the number of tokens received and their value in the currency used for personal planning.
How Staking Works
The process begins by choosing a route. Solo validators run infrastructure and control validator and withdrawal credentials. Native delegators assign stake weight through the network. Pooled services combine smaller balances. Custodial providers control assets and distribute rewards according to their own schedule.
Liquid staking issues a transferable token representing pooled staked assets and rewards. The token can be held, sold, or used in compatible DeFi applications. This flexibility adds smart-contract, governance, liquidity, and depegging risk, and protocol redemption may still require a waiting period.
Solo validation offers direct control but requires technical operations and any protocol minimum.
Native delegation removes server work while retaining on-chain visibility.
Pooled staking allows smaller balances and adds pool or smart-contract dependencies.
Custodial staking is simple to use and transfers control to the provider.
Liquid staking provides a transferable receipt token with additional market risk.
Delegating or Locking Coins
Delegated tokens may remain associated with the owner’s wallet or a dedicated stake account while contributing voting weight to a validator. The operator takes a commission from rewards. Changing validators can require an activation or cooldown period, and newly delegated funds may not earn immediately.
Other staking systems lock tokens in a contract or require a separate stake account. Confirm who controls withdrawal credentials and whether the holder can undelegate without provider approval. A platform balance is not the same as on-chain ownership.
Reward Distribution
Rewards may be added automatically to the stake, credited at the end of an epoch, or made available through a claim transaction. Custodial services can set their own distribution schedule. Liquid-staking protocols may increase the token balance or change the exchange rate between the receipt token and the underlying asset.
Compounding is useful only after fees and risks are considered. Automatic reinvestment keeps more value exposed to the same validator, contract, or custodian. Treat reinvested rewards as a new allocation decision rather than assuming they are already secured profit.
Lock-Up and Withdrawal Periods
Proof-of-stake networks may use activation, deactivation, or unbonding queues. The waiting period can change with network demand. A custodian may add its own processing time, account checks, or minimum withdrawal amount. Review the full path from an exit request to assets arriving in a personal wallet.
Liquid-staking tokens create a faster market exit when buyers and liquidity are available. The sale price can fall below redemption value during stress. Money needed on a specific date should not rely on a secondary market or an uncertain validator exit queue.
Staking vs Crypto Savings
Native staking supports blockchain consensus and pays rewards under protocol rules. A savings account generally uses customer assets in lending or another platform strategy. Staking risk centers on the token, validator, network, and chosen custody route. Savings risk centers on the provider, borrowers, collateral, liquidity, and legal claim.
Liquidity differs by product rather than by label. Native staking can have an unbonding period, while a flexible savings account may allow quick withdrawal in normal conditions. A fixed savings term can be less liquid than delegation. Compare the actual exit rules and who controls them.
Rates also need the same basis. Compare net returns over the same period, after commissions, platform fees, taxes, and inflation. Apply separate price scenarios to the assets received. A larger rate in a weaker or more volatile token is not automatically a better outcome.
Which Should You Choose?
Start with the asset you already want to hold. If it is a proof-of-stake token, compare staking with leaving the same token unstaked. If it is Bitcoin or a stablecoin, a savings product introduces lending or platform risk. Avoid buying an unfamiliar asset solely to access its yield.
Next, map custody and exit. Record who holds the keys, how revenue is created, when the rate can change, how losses are allocated, and how long withdrawal takes. Test the mechanism with a limited deposit before increasing the position.
Choose native staking when protocol participation and on-chain visibility match the goal.
Choose a savings account only after understanding asset use, collateral, and provider solvency.
Use custodial staking after reviewing legal terms and withdrawal history.
Use liquid staking only when the receipt token has a clear purpose.
Keep a liquid reserve outside every yield product.
The better option is the one whose downside fits the investor’s budget and time horizon. A manageable loss limit matters more than an optimistic projection. Write review dates and exit triggers before the account balance begins changing.
Risks to Consider
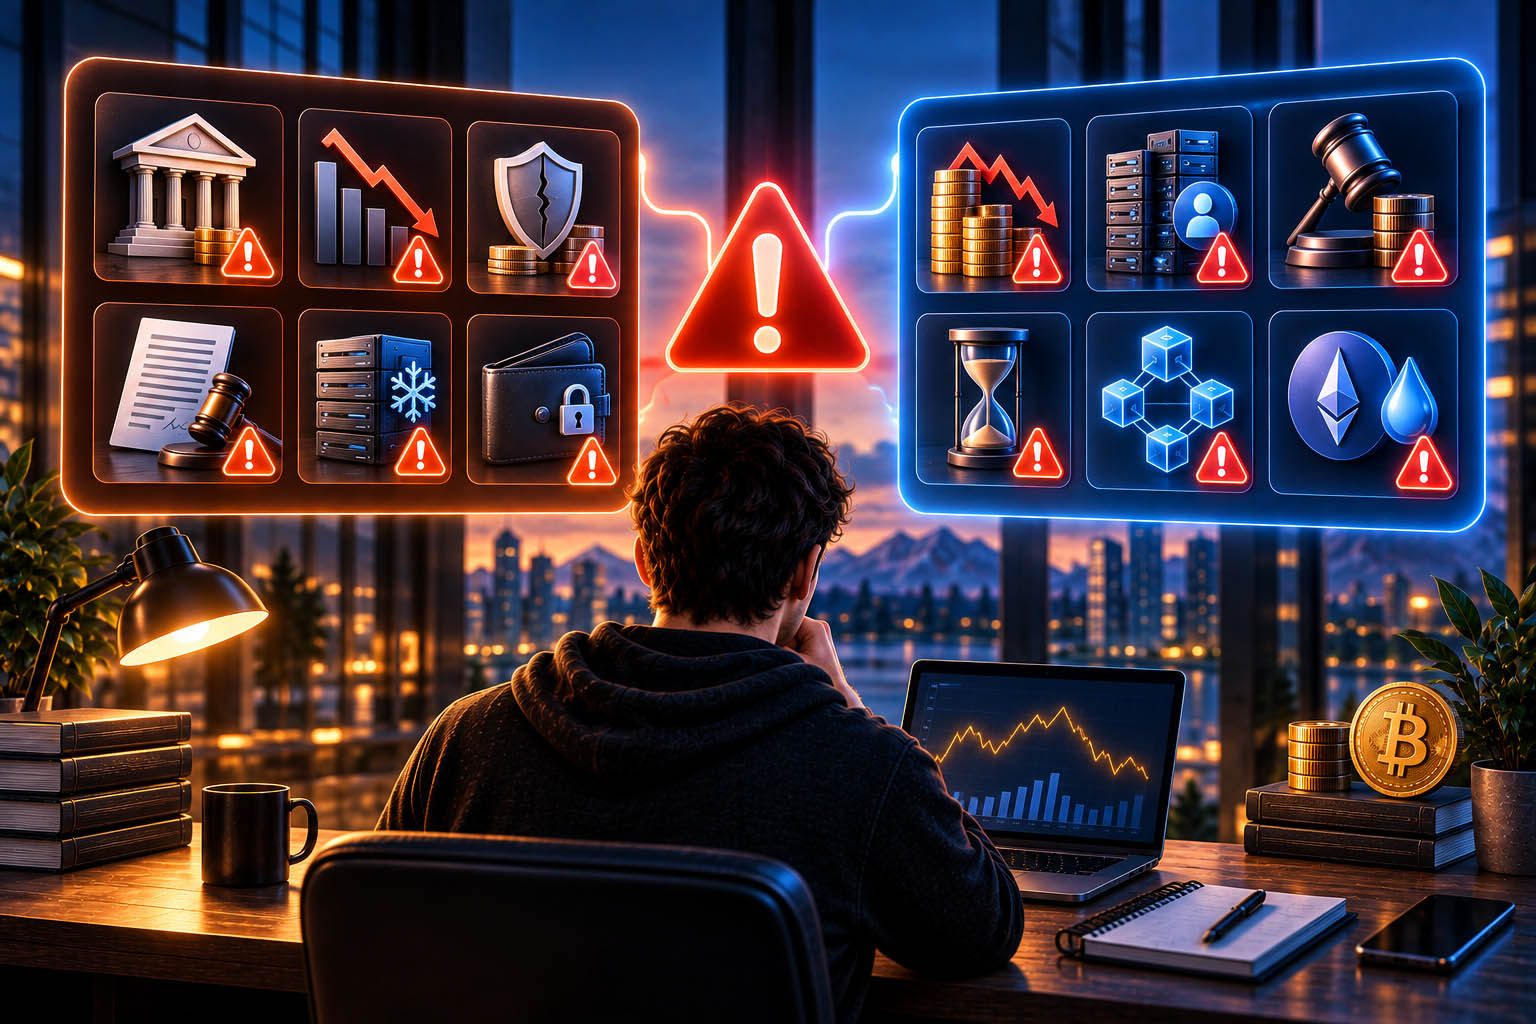
Savings accounts carry counterparty, credit, custody, liquidity, security, and legal risk. Borrowers can default, collateral can fall too quickly, smart contracts can fail, and a platform can freeze withdrawals. A reward credited on a dashboard is not useful if the underlying assets cannot be returned.
Staking carries token-price, validator, penalty, slashing, lock-up, custody, and protocol risk. Liquid staking adds contract, governance, market-liquidity, and depegging exposure. A custodian adds its own solvency and account-access risks on top of the network mechanism.
Verify the company, custody structure, and source of rewards.
Read withdrawal, lock-up, rate-change, and termination terms.
Check validator performance, commission, and slashing policy.
Understand collateral, liquidation, and reserve practices for savings products.
Protect account credentials and withdrawal addresses.
Limit the position to an amount that can withstand a severe loss.
Warning signs include guaranteed returns, pressure to deposit quickly, opaque ownership, unexplained wallet activity, and a rate whose source cannot be described. Pause when records do not reconcile or withdrawal rules change without a clear reason.
Alternative Ways to Earn Crypto Income
DeFi lending can match lenders and borrowers through smart contracts. Liquidity pools pay trading fees and incentives but introduce smart-contract exposure and possible impermanent loss. Some protocols distribute governance tokens for temporary participation, making future yield dependent on the token’s market value.
Running infrastructure, mining, market making, and providing specialized services can also generate crypto income. These activities require different skills, capital, and operating effort. They should be analyzed as businesses or technical strategies rather than as passive savings.
Diversification across several yield products does not eliminate shared risks. Multiple platforms may use the same borrowers, collateral, custodians, stablecoins, or protocols. Map those dependencies before assuming that several account names represent independent exposure.
Key Takeaways
Crypto savings accounts usually earn through lending or another provider-managed strategy.
Native staking earns protocol rewards for supporting proof-of-stake consensus.
Compare net yield, custody, liquidity, asset exposure, and exit rights.
A high rate can reflect temporary incentives, scarce capital, or greater risk.
Start with a limited amount and complete a real withdrawal.
Expert Insight
To earn interest on cryptocurrency responsibly, trace every payment backward. Identify the borrower, validator, protocol, fee source, or business activity that produced it. Then list each party and contract that can delay or reduce repayment. This map is more informative than the advertised APY.
Measure performance first in the deposited asset and then in fiat currency. Keep yield assumptions separate from price assumptions. When actual results diverge, update the model before adding funds or reinvesting rewards.
Conclusion
Crypto savings accounts and staking can increase a token balance, but the reward mechanisms and failure points differ. Savings products depend on a provider and its use of customer assets. Staking depends on a proof-of-stake token, validators, protocol rules, and the chosen custody route.
Begin with a small position, verify the source of yield, understand withdrawal timing, and keep records outside the platform. Compare net results after fees, inflation, and taxes. A suitable strategy remains manageable when rates fall, prices move sharply, or access takes longer than expected.
FAQ
- Can you earn interest on cryptocurrency without selling it?
Yes. Savings accounts, staking, and some DeFi strategies can add tokens while the original position remains open, but each introduces additional risks.
- Are crypto savings accounts insured like bank accounts?
Usually not in the same way. Protection depends on the provider, product, and jurisdiction, so read the legal terms and custody arrangement.
- Is staking safer than a crypto savings account?
Neither is automatically safer. Staking has token, validator, protocol, and custody risk; savings accounts add provider, borrower, collateral, and liquidity risk.
- Can staking rewards change?
Yes. Protocol issuance, total stake, validator performance, commissions, fees, and network activity can all change the net reward rate.
- How quickly can funds be withdrawn?
It depends on the product. Flexible accounts may be quick, fixed terms restrict access, and staking can require activation, unbonding, or custodian processing.
- What should a beginner check first?
Identify the reward source, custody, fees, lock-up, withdrawal route, loss allocation, and provider or validator record before depositing a small test amount.
Published Articles
How to Build and Diversify a Crypto Portfolio and Track Your Assets
Learn what is a crypto portfolio, how to choose and diversify assets, track performance, manage custody, and control common crypto risks.
Bitcoin Wallet for Cloud Mining: How to Choose and Secure Your Wallet
Find the best Bitcoin wallet for cloud mining, compare hardware and software options, and learn how to secure every mining payout.
Degen in Crypto Explained: Meaning, Culture, and Risks
Introduction Not every term that gets coined in crypto culture starts as a compliment. "Degen" — short for degenerate — began as an insult imported from gambling circles. It was later repurposed by crypto traders as a...
What Is Zora? Zora Protocol and Its Ecosystem
Introduction The question most people start with is also the simplest: what is Zora? At the surface level, Zora is a platform for creating and collecting digital content on-chain. Look a little deeper, and it becomes...
Smart Contracts: How Blockchain Automates Digital Agreements
Introduction In 1994, Nick Szabo — a legal scholar and cryptographer — described a concept he called a "smart contracts." He imagined a digital agreement that could enforce its own terms automatically, without needing...
Moonshot Crypto: High-Risk, High-Reward Tokens
Introduction In 2020, Shiba Inu launched with no institutional backing, a novelty premise, and a supply of one quadrillion tokens. By October 2021, it had returned over 800,000% to investors who had bought in early an...